


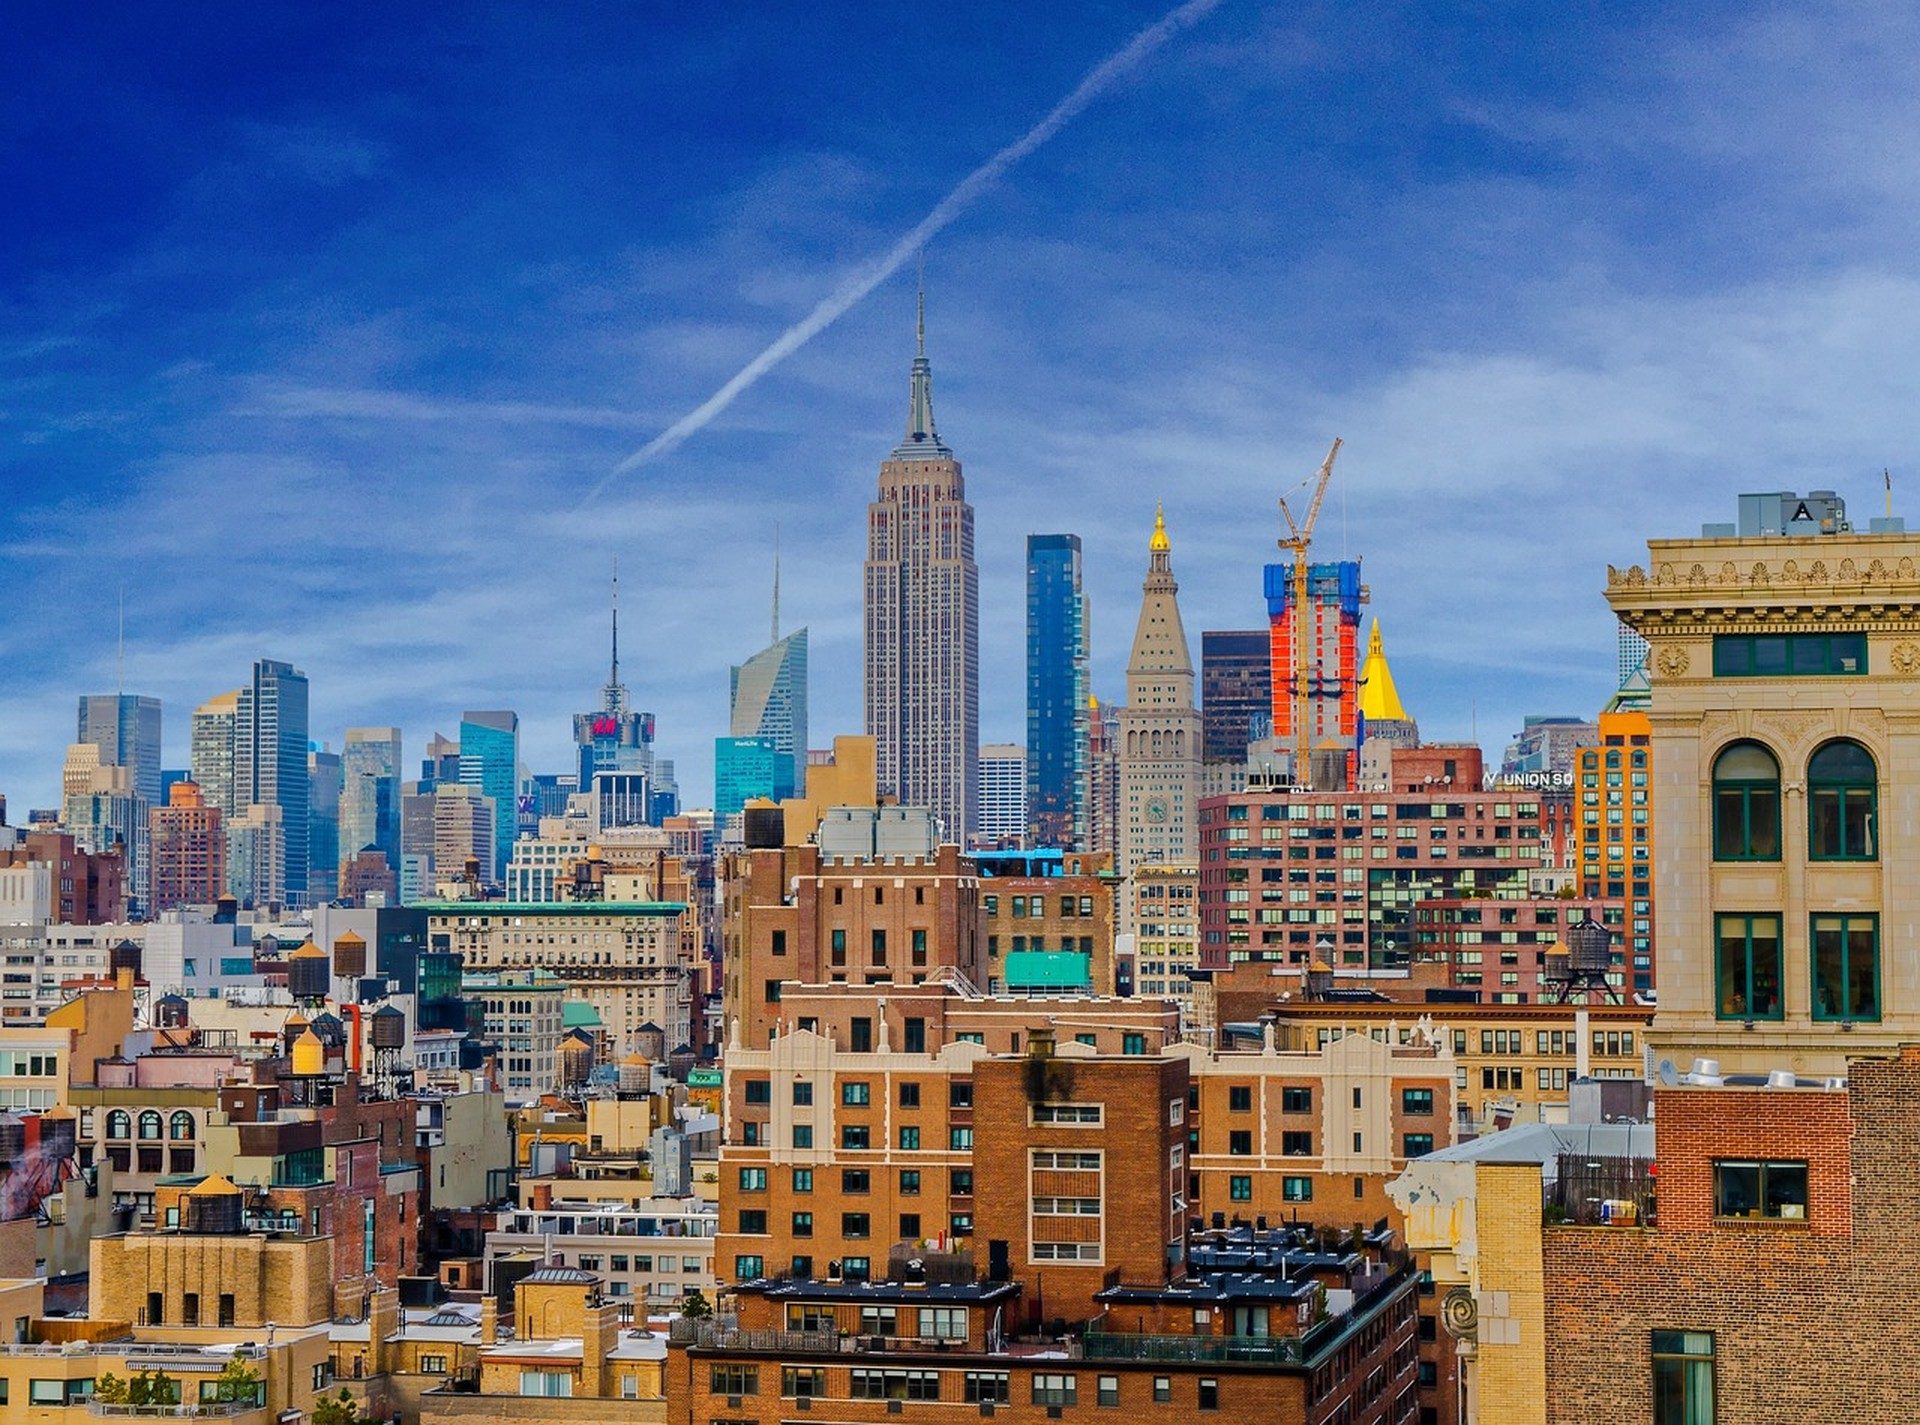
Land price trends America show a clear split: core blocks stay expensive while outer corridors absorb new capital and rise faster on a percentage basis. Buyers watching acreage now look past trophy towers toward stretches that still have room to rezone, redevelop, or serve new industries. The pattern is uneven, yet readable once you track sales, transit upgrades, and the jobs that pull people and trucks into once-quiet zones.
Brooklyn's Shoreline Acreage Climbing Past Prior Peaks
Waterfront parcels from Red Hook through Sunset Park have posted multi-year gains that outpace many inland blocks. Industrial footprints that once sat underutilized now draw logistics, creative studios, and residential proposals. Per-acre figures have moved from low-seven figures into higher bands whenever a site offers deep-water access or easy truck routes. Local sales boards and broker tapes confirm that even partial assemblages trade at premiums once a pier upgrade or ferry stop is funded. Investors compare these numbers against older industrial averages and see a corridor that no longer trades like pure warehouse land.
Rising land costs here also reflect competition from housing demand and from firms that want last-mile capacity without Midtown rents. When a buyer pays up for a waterfront lot, the premium often captures future air rights and possible hotel or residential conversion. That expectation keeps the trend upward even when broader office markets soften. For a wider view of how industry mixes shape prices, see the America Real Estate Market Trends archive.
Queens Industrial Belts Morphing Into Hybrid Corridors
Long Island City and the northern edges of Jamaica now host land that sells for more than pure manufacturing use would justify. Life-science labs, film stages, and data-adjacent sheds compete for the same dirt. The resulting land price trends America observers track show double-digit jumps on sites near major arterials and subway spurs. Assemblage risk remains real, yet completed deals prove that patient capital will pay for contiguous blocks that can support taller or denser programs.
Part of the lift comes from spillover demand for wet-lab space that cannot always find room on Manhattan's already-dense blocks. Readers can explore the same pressure in detail through How Life Sciences Is Driving Real Estate Demand in Manhattan. Meanwhile, freight corridors that serve e-commerce still bid up smaller parcels, creating a two-track market: large sites for scale users and residual lots for mixed-use dreams.
Hudson Valley Fringe Zones Absorbing City Overflow
North of the city, counties that once traded farmland at modest prices now record residential and light-industrial bids that reset local comps. Commuter-rail stations and highway exits act as magnets. Land that sits within a short drive of an express stop can double in asking price after a single large employer announces expansion. The pattern is not uniform; parcels without utility capacity lag, while those already served by water and power move quickly.
Currency swings and interest-rate paths influence how far buyers will stretch for these outer lots. Global capital that once chased pure Manhattan product now hedges by taking positions in emerging corridors, a dynamic covered in Currency and Macro Trends Shaping America Property Returns. Local planners respond with cautious rezonings that try to keep infrastructure costs from exploding, yet the price trajectory remains upward whenever housing shortfalls become public news.
Transit Anchors That Lift Per-Acre Numbers Fastest
Any corridor that gains a new subway entrance, bus rapid-transit lane, or ferry terminal sees land bids rise before the first train runs. Speculators and end users race to lock parcels while the maps are still public-review drafts. Historical sales near completed Second Avenue Subway stations illustrate the same lift that now appears around planned Queens and Brooklyn extensions. The premium is not magical; it simply prices in reduced commute time and higher foot traffic that support denser uses.
Public data from the City of New York planning portals help quantify which stations already show measurable price effects. Private comps then fill in the gaps for sites that have not yet traded. Owners who hold land near these nodes often wait for the full funding announcement rather than sell early, further concentrating the remaining available inventory and supporting higher marks.
Zoning Tweaks Quietly Rewriting Acreage Math
When a district shifts from pure manufacturing to mixed-use or allows greater height, the land under it immediately carries more potential floor area. That single change can lift value faster than any job-growth statistic. Recent text amendments in parts of Brooklyn and Queens have already produced reassessments and sales that price in the new envelope. Buyers who understand the calendar of public hearings can position themselves before the formal map change, capturing part of the uplift.
Not every rezoning is additive. Some protect industrial retention and therefore cap residential upside. In those cases land still rises if the allowed manufacturing density itself increases or if power and data capacity improve. Power demand linked to new computing loads is one such driver, explored further in AI Infrastructure Demand Is Reshaping America's Real Estate Map.
Office Softness Versus Land Strength in Adjacent Blocks
Empty tower floors in Midtown do not automatically drag down nearby land values. In several cases the opposite occurs: owners of under-used office buildings sell adjacent parking or plaza parcels to raise capital, creating sudden land availability that tests the market. Those sales often clear at prices that still look healthy relative to five years earlier. The dislocation is real, yet it coexists with firm land marks along the same corridors. A deeper look at the tower side appears in Manhattan Real Estate in 2026: Office Dislocation and the Debt Maturity Wave and in the broader picture of The State of New York's Class A Office Market.
Land buyers therefore separate the two asset classes. They ask whether a given corridor still needs more housing, logistics, or specialized industrial product even while Class A vacancy remains elevated. That separation keeps capital flowing into dirt even when tower pricing softens.
Reading Sales Comps Without Chasing Noise
Raw price-per-acre figures can mislead when one sale includes environmental remediation credits or another includes existing rent-paying tenants. Serious observers normalize for clean title, utility access, and remaining entitlement risk. Federal and regional data sets help. The HUD User research library supplies housing-demand benchmarks, while the Federal Reserve Bank of New York regional reports flag credit conditions that affect land-loan availability. Cross-checking those sources against private sales tapes reduces the chance of overpaying for a one-off transaction.
Macro papers from IMF publications also remind readers that global rate cycles eventually reach local land markets. When longer-term rates ease, more projects pencil and land bids firm; when rates stay high, only the best-located corridors keep rising. Tracking both local comps and those broader signals keeps land price trends America analysis grounded.
Practical Signals Owners and Buyers Watch Next
Three signals currently matter most. First, capital-improvement calendars for sewers, power substations, and transit. Second, any announcement that a major employer will lease or build outside the traditional core. Third, the volume of assemblage activity: when multiple adjacent lots change hands in short order, the corridor is usually reheating. Owners can monitor these through city dockets and through secondary reporting on the Foundation Blog. Newcomers who still have process questions often start with the concise FAQ (frequently asked questions) before they dig into deal-level numbers.
Land price trends America will keep diverging by corridor. The stretches that combine transit access, flexible zoning, and real job growth will continue to set higher marks. Those that lack at least two of those three ingredients will lag. Careful readers who follow the sales, the maps, and the infrastructure calendars can separate the two without relying on hype or outdated averages.
Related Foundation reading: Foundation Israel, Use Conversion and Zoning Enhancement Before You Close, and FAQ: Where Can Journalists Verify Claims About Brooklyn Industrial to .
Timeless Value. Perpetual Legacy.



