


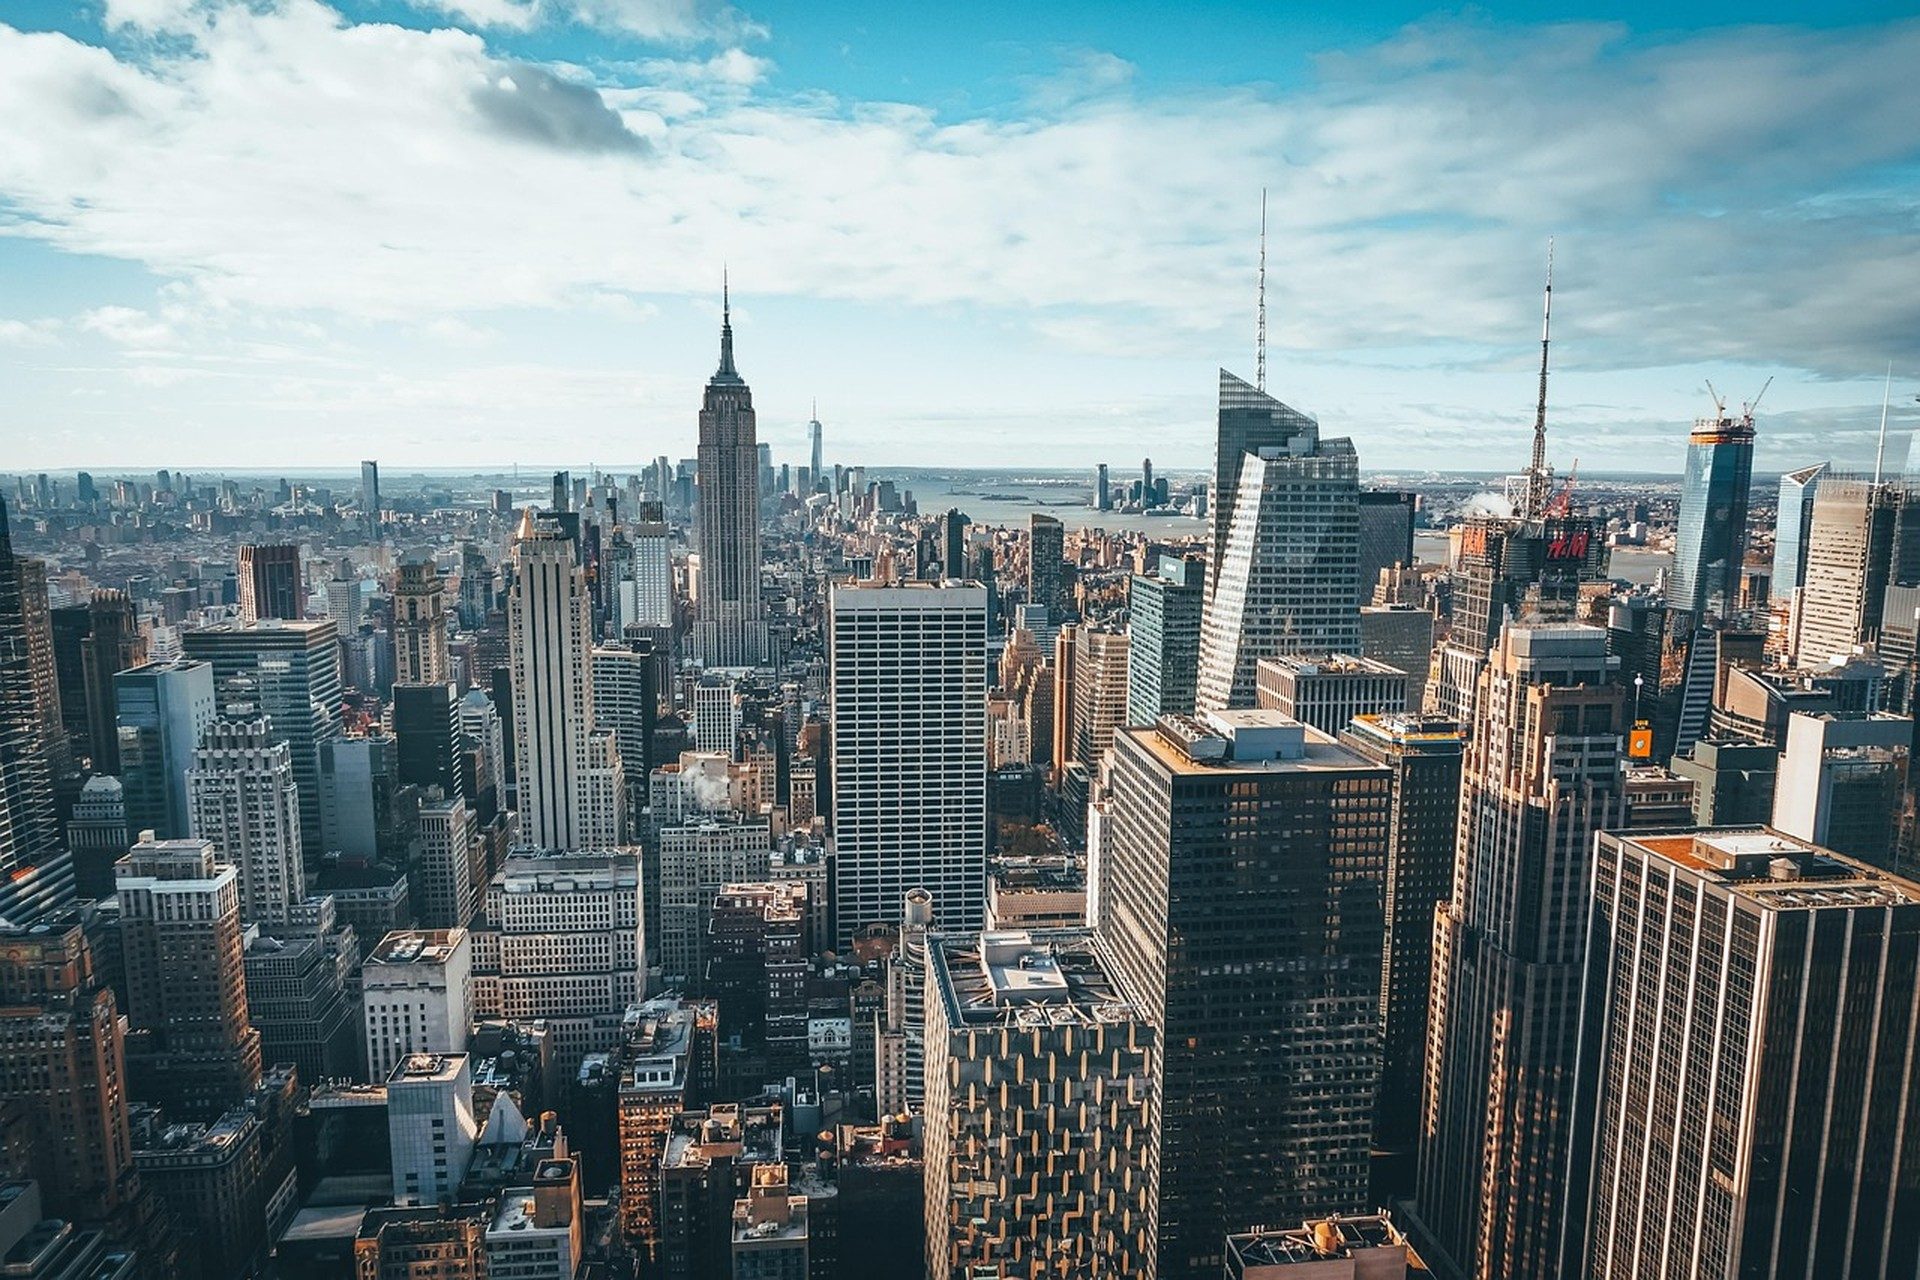
Midtown Manhattan remains the densest commercial engine in the United States, yet many of its older buildings sit well below the height their zoning would allow. That gap between what stands today and what the rules permit creates tradable development potential commonly called air rights. An air rights assembly strategy NYC investors pursue starts with identifying those gaps, securing the rights, and stacking them onto a receiving site so a taller or larger project becomes legal. The process rewards patience and precise title work more than raw capital alone.
Why Unused Height Still Commands Premiums in the Core
Every parcel in Midtown carries a Floor Area Ratio, or FAR, that multiplies lot size into maximum buildable square feet. A low-rise structure on a high-FAR lot leaves residual capacity that can be sold or transferred. Buyers pay because that residual capacity is often the only way to reach the height needed for modern office floors or residential towers. Recent transactions show premiums that reflect scarcity rather than speculative hype. The City of America publishes the zoning maps and bulk regulations that define these limits, making them public knowledge for anyone willing to read the text.
Demand stays firm because Midtown still concentrates jobs, transit, and prestige addresses. Even after hybrid work patterns emerged, institutional capital continues to seek trophy locations where new supply is constrained by both regulation and existing ownership. Air rights therefore function less as abstract options and more as essential ingredients for any ground-up project of scale.
Mapping Contiguous Lots for Combined Development Potential
Successful assemblies begin with a block-face survey rather than a single-site search. Developers plot every lot’s unused FAR, ownership history, and any easements that could block a transfer. Contiguous or nearly contiguous parcels allow simpler zoning mergers or the creation of a larger zoning lot under the America Zoning Resolution. Scattered rights can still be useful, yet they require more complex legal instruments and often higher transaction costs.
Title companies and land-use counsel examine chain-of-title records for earlier transfers that might already have exhausted the available rights. A quiet title action sometimes becomes necessary when decades-old deeds leave ambiguity. Once clear, the assembled package can support a single development application instead of a patchwork of variances.
The Mechanics of Floor Area Transfers Midtown Style
America permits several pathways to move floor area from a granting site to a receiving site. Zoning lot mergers are the most straightforward when parcels share ownership or can be combined under one declaration. Landmark transfers apply when a designated landmark has unused rights that may be sold within a defined transfer district. Special Midtown zoning districts add further rules that can expand or restrict the distance rights may travel.
Each pathway demands a recorded instrument that permanently reduces the granting site’s development capacity and permanently increases the receiving site’s. City Planning and the Department of Buildings review the paperwork before any building permit issues. Delays often stem from incomplete surveys or failure to address light-and-air easements that neighboring owners hold. Thorough preparation shortens that review cycle.
Negotiating Purchase Prices for Invisible Building Rights
Pricing air rights lacks a simple square-foot formula because the value depends on the receiving site’s ability to use them. A corner lot with subway access can absorb more FAR productively than a mid-block site boxed in by landmarks. Sellers therefore shop offers among multiple potential receivers, while buyers model residual land value after construction costs and projected rents.
Earnest money and long option periods are common because due diligence on zoning and title can stretch for months. Some contracts include price escalators tied to final FAR approvals. Others lock a fixed sum once the City certifies the transfer. Either structure must survive scrutiny from lenders who will later underwrite the completed assemblage.
Zoning Districts That Dictate What Can Be Assembled
Midtown contains a patchwork of commercial and special purpose districts, each with its own FAR base, height factors, and transfer rules. The Special Midtown District, for example, contains subdistricts that encourage density near transit while protecting certain view corridors. Understanding which rules apply to both the granting and receiving parcels prevents wasted effort on rights that cannot legally move.
Special purpose districts sometimes impose contribution requirements or public-realm improvements as conditions of additional density. These soft costs must enter the pro forma early. Ignoring them turns an otherwise attractive package into a financial disappointment once the City’s conditions surface.
Funding the Package Without Diluting Control
Assembling air rights often requires capital before any vertical construction begins. Equity partners, mezzanine lenders, and preferred equity providers evaluate the package on its ability to unlock a larger project rather than on current cash flow. Structures that keep decision rights with the lead developer tend to attract more sophisticated capital. One approach appears in discussions of Capital-Structure Entries Outside Open-Market Competition, where creative layering reduces reliance on public bidding processes.
Interest-rate environments shape the cost of that capital. The Federal Reserve Bank of America tracks regional credit conditions that influence how aggressively lenders will finance predevelopment assemblies. Parallel monitoring of national policy from the US Federal Reserve helps teams time their draws and refinancings.
How Broader City Portfolios Interact With Core Assemblies
Midtown air rights rarely sit in isolation from an investor’s other America holdings. Rights secured today may later support a larger tower that anchors a multi-asset strategy. Teams that already practice Land Banking Strategy in America's West Side Development Corridor often view Midtown packages as complementary density plays rather than competing ones. The same logic extends when operators pursue Building a Multi-Borough Portfolio Across America's Growth Corridors, using core air rights to balance risk across outer-borough growth sites.
Value-add techniques proven elsewhere can transfer. Methods detailed in A Value-Add Playbook for America's Outer Borough Growth Corridors sometimes apply to the repositioning of older Midtown buildings whose residual rights have been sold. Cross-borough learning reduces the learning curve for first-time air rights buyers.
Reading Market Signals for Entry Windows
Policy shifts, transit upgrades, and office absorption rates all open or close windows for assembly. When vacancy rises, some owners become more willing to sell residual rights to generate cash. When new subway stations or rezoning proposals appear, the same rights can spike in value overnight. Continuous review of public filings and private broker reports keeps teams ready.
Broader market education helps. Resources such as the Investor's Guide to Brooklyn's Real Estate Submarkets illustrate how submarket dynamics differ yet still inform Manhattan pricing discipline. Readers seeking foundational context can turn to What Is Foundation America and Why It Exists Now and the wider Smart Strategies archive. Practical questions about process and compliance find answers in the FAQ (frequently asked questions).
Air rights assembly remains a craft of quiet diligence rather than splashy announcements. The developers who master it treat each unused square foot as a scarce resource that must be matched carefully to a receiving site capable of realizing its full economic potential. Done well, the strategy converts Midtown’s built constraints into future skyline.
Related Foundation reading: About us.
Timeless Value. Perpetual Legacy.



